Focus on Q4: Macro threats vs. earnings season expectations

September has historically been one of the most challenging months for the stock market, and this year was no exception. During the month, investors had to process a 0.25 percentage point interest rate increase by the US Federal Reserve (Fed), crude oil prices ranging from 100 to110, and hawkish comments about maintaining high interest rates. As the calendar turns to October, the final quarter (Q4) of the year begins for the stock markets. Historically, Q4 has been a strong period for equities, but the direction of travel for the rest of the year will be determined by a tug-of-war between two opposing forces: the impact of a tight interest rate environment and latent inflationary pressures weighed against companies’ the earnings growth potential.
The central bank squeeze and bond market pressure
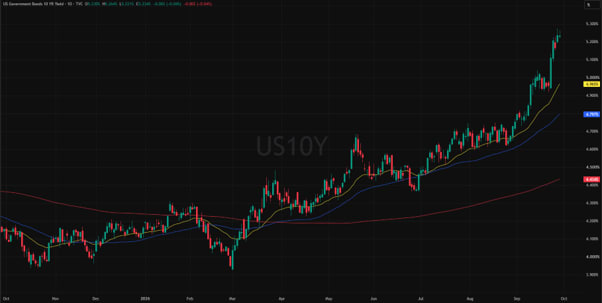
In September, inflation fears returned to the forefront for investors, a trend that was reflected directly in the bond markets. With the price of crude oil remaining near the $100 mark, core inflation is proving stubborn, forcing central banks to maintain a cautious approach.
The US Federal Reserve’s (Fed) interest rate hike of 0.25 percentage points in September, coupled with its message of "higher rates for longer" has pushed up US government bond yields. Rising interest rates reduce the attractiveness of the stock market, particularly for highly valued growth companies. However, the US economy has demonstrated exceptional resilience, keeping recession risks at bay for the time being.
The European Central Bank’s (ECB) interest rate hike to 2.50 percent in September is also takingits toll on European companies. High energy costs are putting pressure on European industry, particularly in Germany, while high interest rates are simultaneously stifling investment. There is now a clear divergence has emerged between the US and European economies, with the US economy proving to be more resilient to interest rates than Europe’s.
US10Y, 1-year chart
US10Y, 5-year chart

Test of the earnings season: Semiconductors and AI at the heart of expectations.
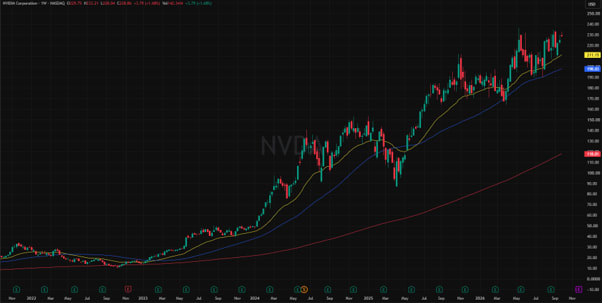
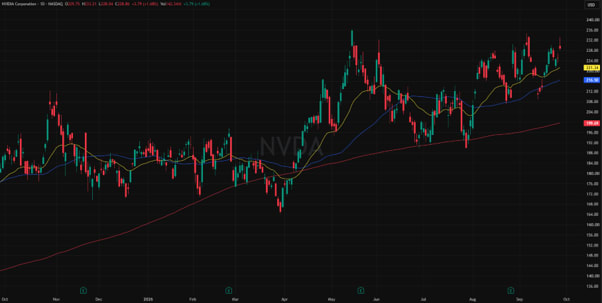
Despite macroeconomic headwinds, both S&P 500 and the NASDAQ have remained close to their record highs, with the latter even reaching new all-time highs. This is largely because stock market earnings growth expectations depend on the shoulders of tech giants and the semiconductor sector. The upcoming Q3 earnings season will need to meet high expectations.
Significant revenue and earnings growth is expected from semiconductor companies such as Nvidia. Investors are also closely monitoring whether hyperscalers such as Microsoft, Amazon, and Google will maintain their substantial investments in massive infrastructure and capital expenditure (CapEx) investments in data centers and AI chips.
In the United States, Q3 earnings forecasts remain strong, specifically driven by the technology sector. In contrast, DAX companies and heavy industry firms in Europe are expressing concern overmargin pressures. This makes the technology sector stand out even more crowded compared to many other sectors.
Related Products
NVIDIA, 1-year chart
NVIDIA, 5-year chart
Starting points for the indices for the Q4 period
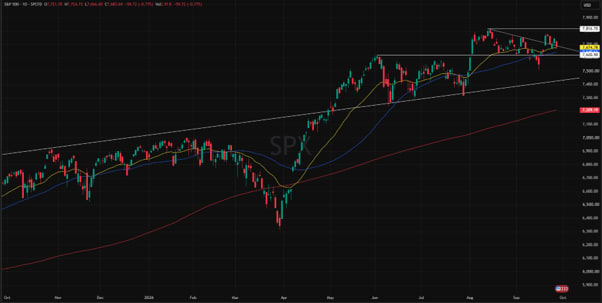
Despite briefly dipping below it in mid-September, the S&P 500 index has managed to remain relatively close to its all-time highs and above the technically significant 50-day simple moving average (blue), which is considered to be a key technical indcatorr. The upcoming earnings season may reveal whether the index can continue its upward trend, which is currently being driven by strong earnings expectations, or whether elevated inflation and interest rates will increasingly erode investor confidence. Disappointing corporate earnings would also introduce further uncertainty into the market.
Related Products
S&P 500, 1-year chart
S&P 500, 5-year chart

Germany’s benchmark DAX index reflects the challenges facing European industry. The index is lagging behind its US counterparts and facing resistance from its short-term moving averages (EMA25 in yellow and SMA50 in blue). High energy costs and the ECB’s tight monetary stance are creating headwinds. To prevent the technical outlook from deteriorating further, the index needs to remain above the key SMA200 moving average (red) to avoid a more pronounced downtrend.
Related Products
DAX, 1-year chart

DAX, 5 – year chart

Summary
Historically, equity market performance during the final quarter of the year has varied across different periods. Looking ahead, market participants are expected to closely monitor developments in bond markets, the interest rate environment and upcoming third-quarter earnings releases, particularly from companies exposed to AI and semiconductor trends. Future market performance cannot be predicted and remains subject to a range of macroeconomic and company-specific factors.
Indicators shown on the charts:
● SMA200: 200-Day Moving Average, red.
● SMA50: 50-Day Moving Average, blue.
● EMA25: 25-Day Exponential Moving Average, yellow.
Risks
Credit risk of the issuer:
Investors in the products are exposed to the risk that the Issuer or the Guarantor may not be able to meet its obligations under the products. A total loss of the invested capital is possible. The products are not subject to any deposit protection.
Currency risk:
If the product currency differs from the currency of the underlying asset, the value of a product will also depend on the exchange rate between the respective currencies. As a result, the value of a product can fluctuate significantly.
Market risk:
The value of the products can fall significantly below the purchase price due to changes in market factors, especially if the value of the underlying asset falls. The products are not capital-protected
Product costs:
Product and possible financing costs reduce the value of the products.
Risk with leverage products:
Due to the leverage effect, there is an increased risk of loss (risk of total loss) with leverage products, e.g. Bull & Bear Certificates, Warrants and Mini Futures.
External author:
This information is in the sole responsibility of the guest author and does not necessarily represent the opinion of Bank Vontobel Europe AG or any other company of the Vontobel Group. This information is sponsored by Bank Vontobel Europe AG, which may be a counterparty to transactions involving the financial instruments discussed in this information. The further development of the index or a company as well as its share price depends on a large number of company-, group- and sector-specific as well as economic factors. When forming his investment decision, each investor must take into account the risk of price losses. Please note that investing in these products will not generate ongoing income.
The products are not capital protected, in the worst case a total loss of the invested capital is possible. In the event of insolvency of the issuer and the guarantor, the investor bears the risk of a total loss of his investment. In any case, investors should note that past performance and / or analysts' opinions are no adequate indicator of future performance. The performance of the underlyings depends on a variety of economic, entrepreneurial and political factors that should be taken into account in the formation of a market expectation.
Disclaimer:
This information is neither an investment advice nor an investment or investment strategy recommendation, but advertisement. The complete information on the products (securities) mentioned herein, in particular the structure and risks associated with an investment, are described in the base prospectus, together with any supplements, as well as the final terms relating to the securities. The base prospectus and final terms constitute the solely binding sales documents for the products mentioned herein. It is recommended that potential investors read these documents before making any investment decision. The documents and the key information document are published on the website of the issuer, Vontobel Financial Products GmbH, Bockenheimer Landstrasse 24, 60323 Frankfurt am Main, Germany, on https://prospectus.vontobel.com and are available from the issuer free of charge. The approval of the prospectus should not be understood as an endorsement of the securities. The securities are products that are not simple and may be difficult to understand. This information includes or relates to figures of past performance. Past performance is not a reliable indicator of future performance. This information may only be distributed or published in countries where such distribution or publication is permitted by applicable law. As stated in the relevant base prospectus, the distribution of the securities mentioned in this information is subject to restrictions in certain jurisdictions. This advertisement may not be reproduced or redistributed without prior permission by Vontobel.
© Bank Vontobel Europe AG and / or affiliated companies. All rights reserved.