A New Equilibrium in the Gold Market

The price of gold has moved within an exceptional environment during the autumn of 2026. Although a strong US dollar and record-high government bond yields create traditional headwinds, the price of the precious metal has demonstrated surprising resilience. The reason for this lies in a structural shift in the market: specifically, massive demand for physical gold from China and geopolitical tensions. Trading in October has been characterized by competing macroeconomic and geopolitical forces. Although the price remains far below the August 2026 highs of around $4,700, it has managed to avoid a deeper slide below $4,000 during October.
Macroeconomic headwinds and the cost of "zero interest rates"
Traditionally, gold tends to suffer when interest rates rise, as the non-yielding precious metal must compete with interest-bearing government bonds. Yields on US government bonds have remained high, while the index measuring the value of the dollar (DXY) has strengthened significantly over the past year.
In addition, fears of inflation are simmering again in the markets. The escalating situation in the Middle East, particularly tensions between the United States and Iran, has kept crude oil prices high. Hotter and more persistent inflation could force the Fed to keep key interest rates "higher for longer," which is essentially toxic for gold.
In a high-interest-rate environment, gold should have experienced a significant and prolonged downward spiral. However, a total collapse has notably failed to materialize. The fact that the price has remained above $4,000 indicates that there are also factors supporting the price of gold.
Bank purchases
One of the major individual reasons for gold's strength lies in the East. In September alone, the People’s Bank of China made its largest monthly gold purchase in nearly three years, increasing its reserves by approximately 23 tonnes.
China has now increased its official gold holdings for a 23 consecutive months. As a result, the country's official gold reserves have risen to a record high of approximately 2,410 tonnes, making China the world's fifth-largest holder of gold, trailing only the United States, Germany, Italy, and France. In 2026 alone, China has officially acquired around 100 tonnes of gold from the market, and when consumer imports are included, customs data indicates that the total volume of gold flowing into the country exceeds 1,000 tonnes (Financial Times, 22.09.2026). If the pace of official reserve accumulation continues, China could overtake France and Italy as early as this year.
The phenomenon involves large-scale strategic "dedollarization", an effort to diversify reserves away from the US dollar and beyond the reach of Western sanctions. Alongside China, Poland has also been an active buyer of gold in recent years.
Related Products
Gold market moves
Although the price of gold has fallen by approximately 25 percent from its peak, the slide has halted for the time being, finding support around the $4,000 mark. Historically speaking, the current price level can still be considered exceptionally high: in the summer of 2026, the price briefly dipped below $4,000, and prior to that, the last time it fell below this level was in 2025.
It is worth noting that the price of gold rose very significantly during 2025 alone, and strong upward momentum continued into the beginning of the current year. After such a sharp rise, a market correction may be considered a normal feature of market cycles.
Throughout October, the price of gold has largely moved within a narrow range of $4,100-4200. On October 7, the market saw a brief, sharper decline, from which the price has nevertheless quickly recovered to a higher level.
Although the price has shown signs of recovery in the short term, the longer-term picture, viewed through the lens of technical analysis, calls for caution. Since the August 2026 highs, the price has fallen below key moving averages (EMA25, SMA50, and SMA200). The alignment of these moving averages now reflects a textbook downtrend, indicating that longer-term momentum currently lies with the bears. Thus, gold’s current technical setup does not exhibit the characteristics of a classic uptrend.
From a historical perspective, it is also essential to remember that gold price movements can be extremely sharp and rapid in either direction, especially when macroeconomic shocks or geopolitical news emerge.
GOLD, 5 year graph
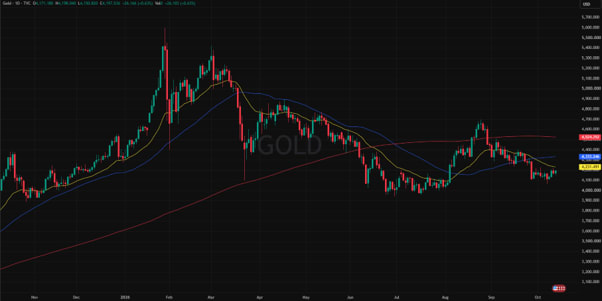
GOLD, 1 year graph

Summary
The gold market is balancing between conflicting forces. Short-term price movements and volatility are driven by the US interest rate market, the strength of the dollar, and anxiety surrounding geopolitical crises.
However, continued demand from central banks provides a floor for the price of gold. Central bank demand may provide support for gold prices, although there can be no assurance that such demand will offset future declines.
Indicators shown on the graphs:
- SMA200: 200-day moving average, red.
- SMA50: 50-day moving average, blue.
- EMA25: 25-day exponential moving average, yellow.
Risks
Credit risk of the issuer:
Investors in the products are exposed to the risk that the Issuer or the Guarantor may not be able to meet its obligations under the products. A total loss of the invested capital is possible. The products are not subject to any deposit protection.
Currency risk:
If the product currency differs from the currency of the underlying asset, the value of a product will also depend on the exchange rate between the respective currencies. As a result, the value of a product can fluctuate significantly.
Market risk:
The value of the products can fall significantly below the purchase price due to changes in market factors, especially if the value of the underlying asset falls. The products are not capital-protected
Product costs:
Product and possible financing costs reduce the value of the products.
Risk with leverage products:
Due to the leverage effect, there is an increased risk of loss (risk of total loss) with leverage products, e.g. Bull & Bear Certificates, Warrants and Mini Futures.
External author:
This information is in the sole responsibility of the guest author and does not necessarily represent the opinion of Bank Vontobel Europe AG or any other company of the Vontobel Group. This information is sponsored by Bank Vontobel Europe AG, which may be a counterparty to transactions involving the financial instruments discussed in this information. The further development of the index or a company as well as its share price depends on a large number of company-, group- and sector-specific as well as economic factors. When forming his investment decision, each investor must take into account the risk of price losses. Please note that investing in these products will not generate ongoing income.
The products are not capital protected, in the worst case a total loss of the invested capital is possible. In the event of insolvency of the issuer and the guarantor, the investor bears the risk of a total loss of his investment. In any case, investors should note that past performance and / or analysts' opinions are no adequate indicator of future performance. The performance of the underlyings depends on a variety of economic, entrepreneurial and political factors that should be taken into account in the formation of a market expectation.
Disclaimer:
This information is neither an investment advice nor an investment or investment strategy recommendation, but advertisement. The complete information on the products (securities) mentioned herein, in particular the structure and risks associated with an investment, are described in the base prospectus, together with any supplements, as well as the final terms relating to the securities. The base prospectus and final terms constitute the solely binding sales documents for the products mentioned herein. It is recommended that potential investors read these documents before making any investment decision. The documents and the key information document are published on the website of the issuer, Vontobel Financial Products GmbH, Bockenheimer Landstrasse 24, 60323 Frankfurt am Main, Germany, on https://prospectus.vontobel.com and are available from the issuer free of charge. The approval of the prospectus should not be understood as an endorsement of the securities. The securities are products that are not simple and may be difficult to understand. This information includes or relates to figures of past performance. Past performance is not a reliable indicator of future performance. This information may only be distributed or published in countries where such distribution or publication is permitted by applicable law. As stated in the relevant base prospectus, the distribution of the securities mentioned in this information is subject to restrictions in certain jurisdictions. This advertisement may not be reproduced or redistributed without prior permission by Vontobel.
© Bank Vontobel Europe AG and / or affiliated companies. All rights reserved.